I know a low unit price can make an order attractive. But missing freight, destination charges or tax funding can leave the purchasing budget incomplete.
I calculate night light landed cost by adding the goods, transport, insurance, import duty and other non-recoverable costs needed to reach a named warehouse. I show recoverable VAT separately, then divide the relevant total by the saleable quantity. I confirm the quotation terms first to avoid counting charges twice.
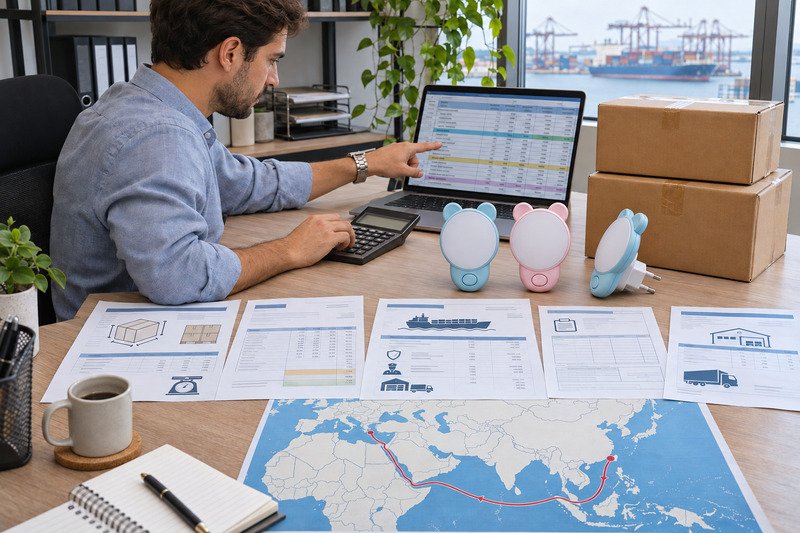
At Chocolamp, I can provide the quotation and packing information needed to begin this calculation. The importer, forwarder and customs broker then contribute the destination-specific figures.
I use a Z-035 shipment to Greece as the packing example below. The shipment quantities and carton data come from a packing list. I use US$0.80 as an illustrative unit price. Every logistics amount in the example is hypothetical, rather than an actual quotation or a customer’s paid expense.
What Does FOB Xiamen Include in the Calculation?
I start with the agreed delivery terms because overlapping supplier and forwarder charges can distort a budget before the goods leave China.
Under FOB Xiamen, I treat delivery on board the buyer-nominated vessel at Xiamen as the agreed delivery and risk-transfer point. The seller handles export clearance, while the buyer arranges the main carriage. I reconcile the actual quotations so export-side services already included in the price are not charged twice.
I define where “landed” ends
For this example, I define landed cost as the cost of getting the goods to a named warehouse in Greece, before onward selling and distribution expenses.
That endpoint matters. Delivery to a port and delivery to a warehouse involve different costs.
I ask the buyer to identify the warehouse location before requesting a complete logistics quotation.
| Cost area | How I review it |
|---|---|
| Goods and agreed export-side services | I check what the supplier’s FOB price includes. |
| Main international carriage | I obtain the buyer’s forwarder quotation. |
| Cargo insurance | I include it if purchased and confirm whether it is already bundled. |
| Destination handling and clearance | I request an itemized breakdown. |
| Import duty and taxes | I obtain the appropriate customs and tax calculations. |
| Warehouse delivery | I confirm the destination address and delivery conditions. |
I reconcile charges by service
I do not add a line called “origin charges” without understanding its contents.
I compare the supplier’s scope with the forwarder’s breakdown. If two lines appear to cover the same service, I clarify responsibility before adding both.
For container-terminal handovers, I also review whether FCA would describe the actual delivery arrangement more accurately. The contract should state the agreed term, location and Incoterms edition.
Which Packing Details Do I Need for a Freight Quotation?
I cannot estimate freight reliably from the product quantity alone. Carton dimensions and gross weight help the forwarder identify the shipment’s actual transport requirements.
I provide the total units, carton count, outer dimensions, gross weight, handover details, destination and proposed shipping date. I also disclose palletization or other packing changes. For an LCL quotation, I ask how chargeable volume or weight, minimums and destination fees are calculated.
I establish the shipment inputs
The Z-035 packing example contains equal quantities of blue and pink night lights.
| Shipment input | Packing-list information |
|---|---|
| Blue quantity | 5,184 units |
| Pink quantity | 5,184 units |
| Total quantity | 10,368 units |
| Quantity per carton | 288 units |
| Carton count | 36 cartons |
| Outer carton dimensions | 59 × 48.5 × 65 cm |
| Total gross weight | 648 kg |
| Calculated carton volume | Approximately 6.696 m³ |
I check the volume using dimensions in meters:
0.59 × 0.485 × 0.65 × 36 = 6.69591 m³
I use gross shipping weight, rather than product net weight, for the transport enquiry.
I ask for a complete route quotation
My enquiry also confirms:
- The agreed handover point and services.
- The destination port and warehouse address.
- Whether the shipment will be palletized.
- The proposed departure period.
- The charging basis and minimum charges.
- The included and excluded destination services.
- Any quotation validity period.
I do not assume that the packing list establishes the shipping method or final freight bill.
When comparing alternatives from our children’s night lights range, I review packing efficiency alongside the product price. A smaller unit-price difference may be outweighed by a larger packed volume.
How Do I Build an Itemized Landed-Cost Example?
I want every budget line to have a clear purpose and evidence status. That makes assumptions easy to replace when actual quotations arrive.
I multiply quantity by the illustrative unit price, then add separately identified logistics costs. I keep unconfirmed duty and VAT outside the completed subtotal. I also use one budget currency and record the exchange-rate basis so the calculation remains traceable.
I calculate the illustrative goods value
For this example, I use:
10,368 units × US$0.80 = US$8,294.40
The US$0.80 figure is a teaching input. It is not presented as the actual invoiced price for this shipment or a current offer.
The following logistics figures are also invented teaching inputs.
| Cost item | Illustrative amount, USD | Evidence status |
|---|---|---|
| Goods value | 8,294.40 | Based on the US$0.80 price assumption |
| International freight | 900.00 | Hypothetical |
| Cargo insurance | 40.00 | Hypothetical |
| Destination handling | 450.00 | Hypothetical |
| Customs brokerage | 150.00 | Hypothetical |
| Delivery to warehouse | 250.00 | Hypothetical |
| Subtotal before duty and VAT | 10,084.40 | Incomplete illustrative budget |
I have not added import duty because the classification and applicable duty have not been confirmed.
I keep missing costs visible
I add inspection, bank charges, storage or other directly attributable expenses where they actually arise and fit the costing purpose.
I also check whether a forwarder’s package price already includes brokerage or delivery. I would replace the individual assumptions accordingly rather than add the package on top.
These illustrative figures exclude separately recoverable service VAT. Any non-recoverable taxes or additional costs need their own treatment.
I convert actual quotations into a consistent budget currency. I keep that commercial budget separate from the currency-conversion rules used for the customs declaration.
How Do I Confirm Import Duty and Treat Import VAT?
I do not select a tariff rate from the description “LED night light” alone. I need the actual product classification and import circumstances before completing the tax section.
I ask the customs broker to confirm classification, origin, customs value and the applicable tariff measures. I calculate import VAT from its confirmed statutory base. I then distinguish VAT funding from permanent product cost because an eligible importer may deduct import VAT, subject to the relevant conditions and documents.
I confirm classification before entering a duty rate
I ask the broker to review the product’s construction and functions. Products within our traditional night lights and multi-functional night lights ranges should not receive an assumed classification merely because both are sold as night lights.
For the Greek example, I request confirmation of:
- The applicable CN/TARIC classification.
- The goods’ origin.
- The relevant import date and tariff measures.
- The customs valuation and required adjustments.
- The resulting duty amount.
For percentage-based duty, the calculation is:
Import duty = confirmed customs value × applicable duty rate
I do not assume customs value equals either the FOB invoice or the full warehouse cost.
I calculate VAT from the correct base
Import VAT is not necessarily calculated on the goods invoice alone. Its base includes customs value and applicable additions, including duty and qualifying incidental expenses that have not already been included.
I ask the broker to establish that base and the applicable VAT rate. I do not use the hypothetical logistics table as a completed Greek tax declaration.
I maintain separate cash and cost views
An eligible taxable importer using the goods for taxed activities may deduct import VAT, subject to the applicable conditions and evidence.
| View | What I include |
|---|---|
| Funding requirement | I include amounts payable under the actual payment arrangement, including VAT that needs financing. |
| Product-cost calculation | I include relevant non-recoverable costs and exclude VAT confirmed as recoverable. |
I ask the importer’s accountant to confirm deductibility and timing. A possible deduction does not automatically remove the initial funding need.
How Do I Allocate the Total to Each Saleable Night Light?
I want the unit calculation to reflect what the buyer can actually sell. Ordered quantity and saleable received quantity may differ, so I verify the denominator.
I divide the relevant warehouse cost by the saleable quantity. I use all 10,368 units only if that quantity is available for sale. I update the calculation for verified shortages or unsaleable stock and use a suitable allocation basis when a shipment contains materially different products.
I calculate the preliminary subtotal per unit
Using the incomplete teaching subtotal:
US$10,084.40 ÷ 10,368 = approximately US$0.973 per unit
This figure excludes duty, VAT treatment and any remaining costs. I would not present it as a final landed-cost quotation.
If confirmed duty is D and other remaining non-recoverable costs are C, the example becomes:
Unit cost = (US$10,084.40 + D + C) ÷ saleable units
I use actual receiving information
I do not invent a damage percentage.
After arrival, I check quantities received and document any shortages or unsaleable units. I then update the calculation using the appropriate treatment of losses, claims and recoveries.
For mixed-product shipments, I may allocate freight by volume or chargeable weight and assign direct costs to the relevant SKU. I document the method instead of dividing every expense equally across unlike products.
I reconcile the budget after delivery
Before closing the calculation, I confirm:
- Supplier invoice and packing quantities.
- Actual freight and destination invoices.
- Insurance charges.
- Customs duty and valuation.
- VAT deductibility.
- Warehouse delivery charges.
- Saleable received quantity.
At this shipment quantity, each additional US$100 of non-recoverable cost adds approximately US$0.00965 per unit. I use that relationship to trace unit-cost changes back to their underlying charges.
Conclusion
I turn an FOB price into a useful landed-cost estimate by checking charge boundaries, packing data, customs calculations, VAT treatment and saleable quantities.